Kenya’s banks expanded. Did businesses benefit?
Kenya’s banks expanded. Did businesses benefit?
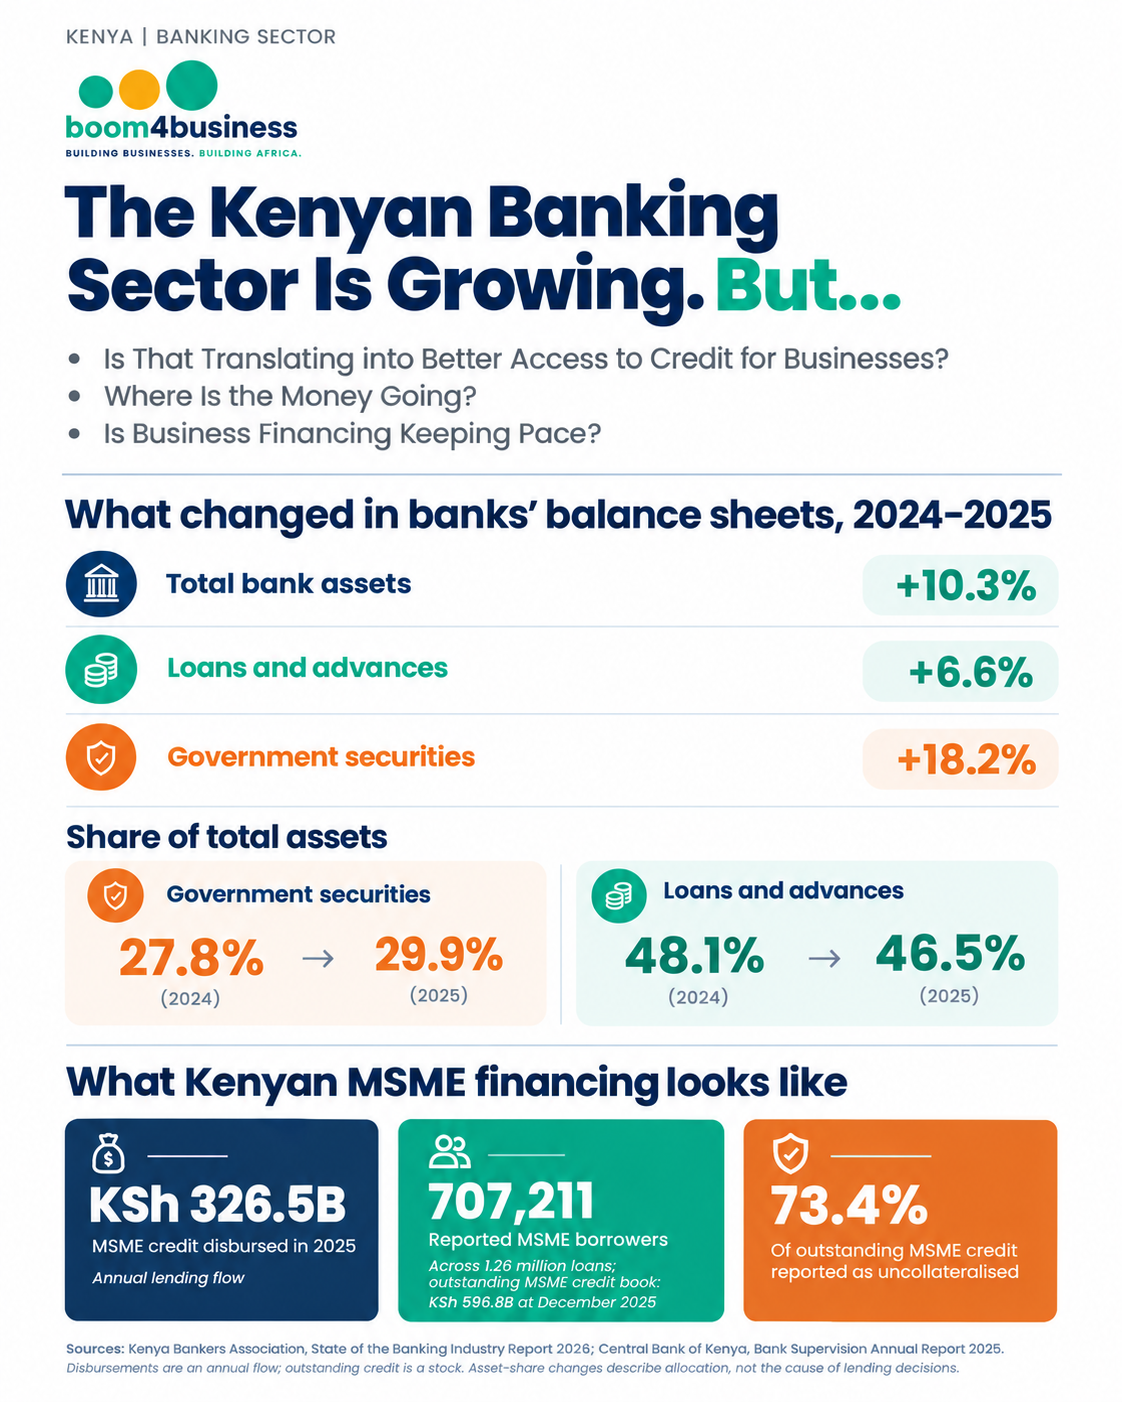
The Kenya Bankers Association’s State of the Banking Industry Report 2026 shows a growing sector, but questions remain about business financing.
Kenya’s banks expanded. Did businesses benefit?
The CBK reports bank assets grew by KSh 781.8 billion (10.3%) to KSh 8.35 trillion in 2025. Government securities rose by KSh 384.5 billion (18.2%), while loans and advances grew by KSh 240.5 billion (6.6%).
Government securities increased from 27.8% to 29.9% of bank assets; loans and advances fell from 48.1% to 46.5%.
Lending occupied a smaller share of a growing balance sheet. This does not prove #banks are withholding credit from viable businesses, but it raises questions about how resources reach the private sector.
The CBK’s 2024 MSME credit survey found banks and #microfinance banks received applications worth KSh 872.6 billion across 2023–24 and approved KSh 771.1 billion by value—an 88.4% approval rate by value, not by number of businesses.
Active MSME loan accounts fell 24.7%, from 1.18 million in December 2022 to 890,000 in December 2024, while the outstanding portfolio remained broadly unchanged at KSh 784.3 billion. The CBK attributes the decline partly to loan clean-ups, repayments and closures. Account numbers alone do not show how access changed.
The KBA reports KSh 326.5 billion in MSME #credit disbursements during 2025. Separately, outstanding MSME credit stood at KSh 596.8 billion at year-end, across 1.26 million loans and 707,211 borrowers. Disbursements are a yearly flow; outstanding credit is a stock.
Cost and distribution matter, too. In December 2024, average MSME interest rates were 16.4% at commercial banks and 26.3% at microfinance banks. The KBA reports 73.4% of outstanding MSME credit was uncollateralised. Yet barriers remain. Women-led enterprises represented 46% of unique MSME borrowers but held 25% of outstanding credit.
Across 23 African countries, the OECD’s Africa Capital Markets Report 2025, drawing on World Bank Enterprise Surveys, found access to finance was the leading business obstacle for 31% of respondents.
For East African businesses, is financing available at the right scale, price and duration to support investment, working capital and growth?
A growing banking sector measures financial expansion. Whether that expansion meets businesses’ financing needs is a separate question.
What evidence would show whether banking-sector growth is translating into better financing and stronger business outcomes?
Sources: CBK, Bank Supervision Annual Report 2025; CBK, 2024 Survey on MSME Access to Bank Credit; KBA, State of the Banking Industry Report 2026; OECD, Africa Capital Markets Report 2025.
—
Documenting the grit and genius of African entrepreneurship with Boom4Business™, straight from the frontline.
I’m Samuel Kimani. I study how African ventures operate when things get unclear, constrained or difficult, then turn those patterns into practical venture intelligence. Follow me if the conversation is useful.
Enjoyed this?
Get the next one in your inbox.